


Credit management is how a business decides who gets credit, on what terms, and how receivables are collected and protected. An outsourced CFO improves credit management by tightening credit policy, scoring customer risk, and speeding collections, which protects cash flow and access to capital. It matters because the Treasury reports that over 20% of SME loan applications are rejected and another 28% are only partly funded.
Key Takeaways
- Credit management is the process of setting credit terms, scoring customer risk, collecting receivables, and enforcing policy.
- An outsourced CFO strengthens it by auditing credit policy, setting risk-based limits, and cutting Days Sales Outstanding (DSO).
- The Treasury reports over 20% of SME loan applications are rejected and 28% are only partly funded, so credit health directly affects access to capital.
- Key metrics to track include DSO, aging buckets, bad-debt ratio, and percentage of overdue accounts.
- You get this expertise on a contract basis instead of a full-time hire, so you pay only for the hours you need.
What is Credit Management and Why Is It Important?
Credit management is the process of deciding who receives credit, on what terms, and how receivables are collected and enforced. It matters because slow-paying and unpaid accounts drain the cash a business needs to operate, so disciplined credit practices protect both liquidity and access to financing.
What Is Credit Management?
Credit management is the structured process of granting credit, establishing payment terms, collecting receivables, and enforcing credit policy. A robust credit management approach directly affects business health.
Studies show that 27% of small firms couldn’t secure needed financing due to weak credit systems, while 46% rely on personal credit cards, exposing them to risk. Strong credit management reduces default risk, prevents cash flow disruptions, and supports credit risk management.
How Does Credit Management Protect Cash Flow?
As the business transitions into operational strategies, credit management becomes essential for safeguarding liquidity and CFO cash flow management. A strategic approach ensures timely collections, avoids extended cash conversion cycles, and sustains working capital.
Key components include:
- Monitoring Days Sales Outstanding (DSO): Reducing DSO accelerates cash inflows.
- Balancing Receivables & Payables: Minimizing cash gaps between customer payments and supplier obligations strengthens stability.
- Utilizing Cash Flow Forecasting: Predicting shortfalls enables proactive credit control.
- Maintaining Adequate Liquidity: Holding 2–3 months of operating expenses helps buffer delays in receivables.
How Does an Outsourced CFO Improve Credit Management?
An outsourced CFO improves credit management by auditing existing credit policy, scoring customer risk, setting clear limits and terms, and tightening collections. The result is a shorter cash conversion cycle and lower bad-debt exposure, delivered on a contract basis instead of through a full-time hire.
Reviewing Current Credit Policies and Identifying Areas for Improvement
A skilled outsourced CFO starts by auditing existing credit policies, including terms, approval workflows, and enforcement. They identify gaps in collection procedures or inconsistent credit limits. They benchmark policies against best practices and regulatory standards.
- Map Policy Effectiveness: Identify approvals causing delays or defaults.
- Spot Inconsistent Terms: Varying credit durations impact cash flow.
- Benchmark Policies: Ensure compliance and consistency.
Implementing Credit Risk Mitigation Strategies
An outsourced CFO then embeds risk mitigation strategies into daily operations. They use credit scoring tools to assess customer risk, adjusting terms accordingly. They also advocate for credit insurance or factoring for high-risk accounts.
By integrating dynamic risk profiles and insurance, businesses significantly reduce exposure to bad debt. This approach reinforces credit management services and supports business resilience through proactive risk oversight.
Optimizing Cash Flow Through Better Credit Control
Optimizing credit control is vital to supply liquidity and improve credit management. An outsourced CFO sets clear credit limits, adjusts terms based on payment history, and automates reminders.
This discipline directly enhances CFO cash flow management, ensuring consistent revenue inflows and minimizing reliance on external working capital.
How Do You Reduce Late Payments and Manage Receivables?
Reducing late payments starts with disciplined receivable processes: automated invoicing and reminders, a defined escalation path for overdue accounts, and regular reviews of aging balances. An outsourced CFO installs this workflow so collections stay consistent instead of ad hoc:
- Implement automated invoicing and reminders to increase on-time payments.
- Set an escalation protocol and apply late fees systematically.
- Conduct regular receivables reviews and follow-ups on aging balances.
Enhancing Credit Reporting and Financial Forecasting
Finally, an outsourced CFO enhances credit reporting systems, tracking KPIs like DSO, aging buckets, and bad-debt ratios. They integrate credit metrics into financial forecasting models. This enables predictive insights into cash flow, allowing businesses to adjust credit strategies before issues arise.
| Metric | What it measures | Why the CFO watches it |
|---|---|---|
| Days Sales Outstanding (DSO) | Average days to collect after a sale | A rising DSO ties up cash and signals weakening collections |
| Aging buckets | Receivables grouped by 0-30, 31-60, 61-90, 90+ days | Shows where risk is concentrating before it becomes bad debt |
| Bad-debt ratio | Write-offs as a share of total credit sales | Measures how well credit policy is protecting margin |
| Percentage of overdue accounts | Share of receivables past their due date | Early warning that terms or enforcement need tightening |
| Cash conversion cycle | Days between paying suppliers and collecting from customers | The core working-capital efficiency number credit policy moves |
Key Strategies for Improving Credit Management with an Outsourced CFO
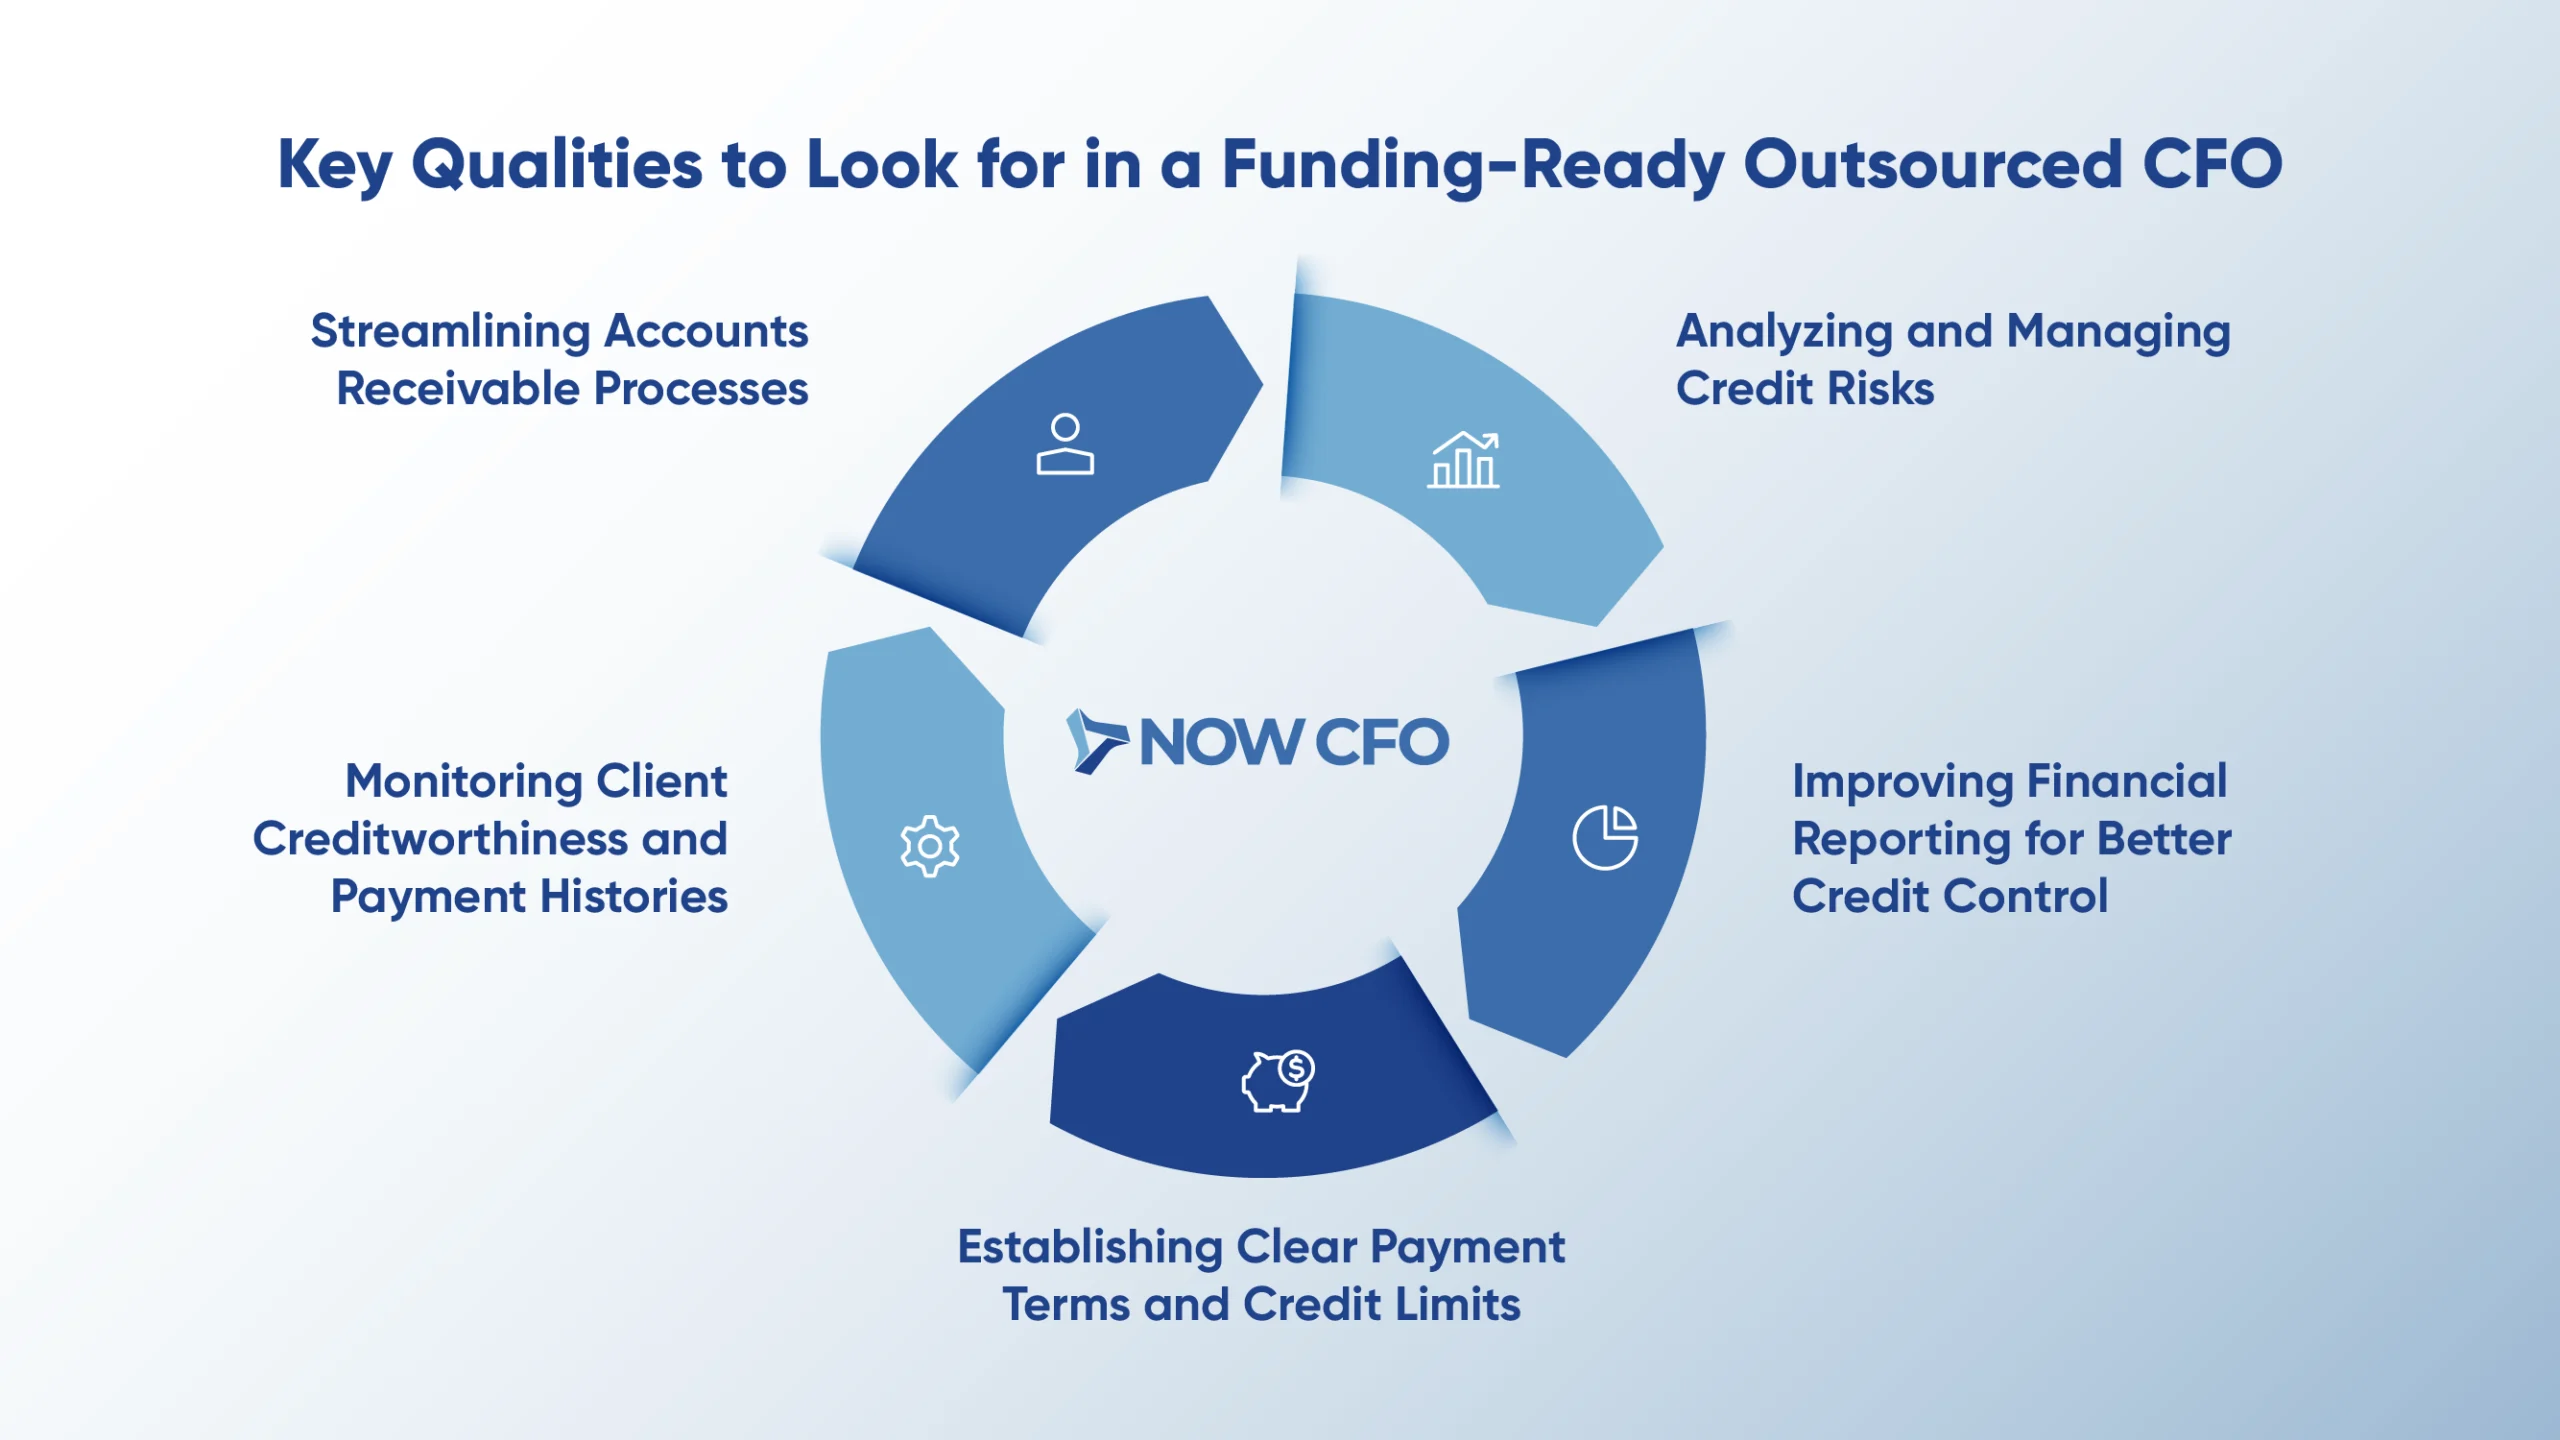
The five core strategies are risk assessment, receivables management, clear credit terms and limits, ongoing creditworthiness monitoring, and credit reporting. An outsourced CFO applies all five so credit decisions stay consistent and cash inflows stay predictable.
Analyzing and Managing Credit Risks
An outsourced CFO begins by quantifying and segmenting credit risk across customer portfolios. They apply standardized scoring systems and categorize clients into low, medium, and high-risk buckets. They then tailor credit exposure limits, adjust terms proactively, and monitor macroeconomic signals that affect client solvency.
Streamlining Accounts Receivable Processes
Next, the outsourced CFO optimizes accounts receivable through disciplined process workflows. They centralize invoicing, implement scheduled follow-ups, and segment aging invoices by risk level.
They define escalation protocols for overdue accounts and ensure collections are consistent and appropriately escalated. By refining credit management services and reducing DSO, businesses enjoy faster cash realization and strengthened working capital cycles.
Establishing Clear Payment Terms and Credit Limits
Building on these foundations, an outsourced CFO crafts unambiguous credit agreements that drive reliable cash flow.
- Standardized payment terms (e.g., Net 30/60/90) based on client risk.
- Define credit caps correlated to client financial strength.
- Include incentives or penalties for early or late payments.
Monitoring Client Creditworthiness and Payment Histories
To maintain control, regular review of client financial health is essential. An outsourced CFO sets periodic assessments, leveraging updated credit scores, payment timeliness, and financial trends. They use this data to re-evaluate credit limits, pause risky accounts, or offer revised terms.
Improving Financial Reporting for Better Credit Control
Finally, the outsourced CFO integrates credit metrics, like DSO, aging buckets, and bad-debt ratios. They prepare dashboards that highlight aging risks, credit exposures by client, and trends in payment behavior.
These insights feed into monthly forecasts, enabling predictive adjustments to credit programs before issues arise. With transparent credit management services reporting, leadership gains clarity and confidence in the health of receivables.
Learn More: Outsourced CFO For Your Business
How Does an Outsourced CFO Mitigate Credit Risk?
An outsourced CFO mitigates credit risk by assessing each customer’s creditworthiness, setting risk-based credit limits, adding credit insurance where exposure is high, and reviewing accounts as conditions change. Structured assessment replaces guesswork, so bad-debt write-offs fall.
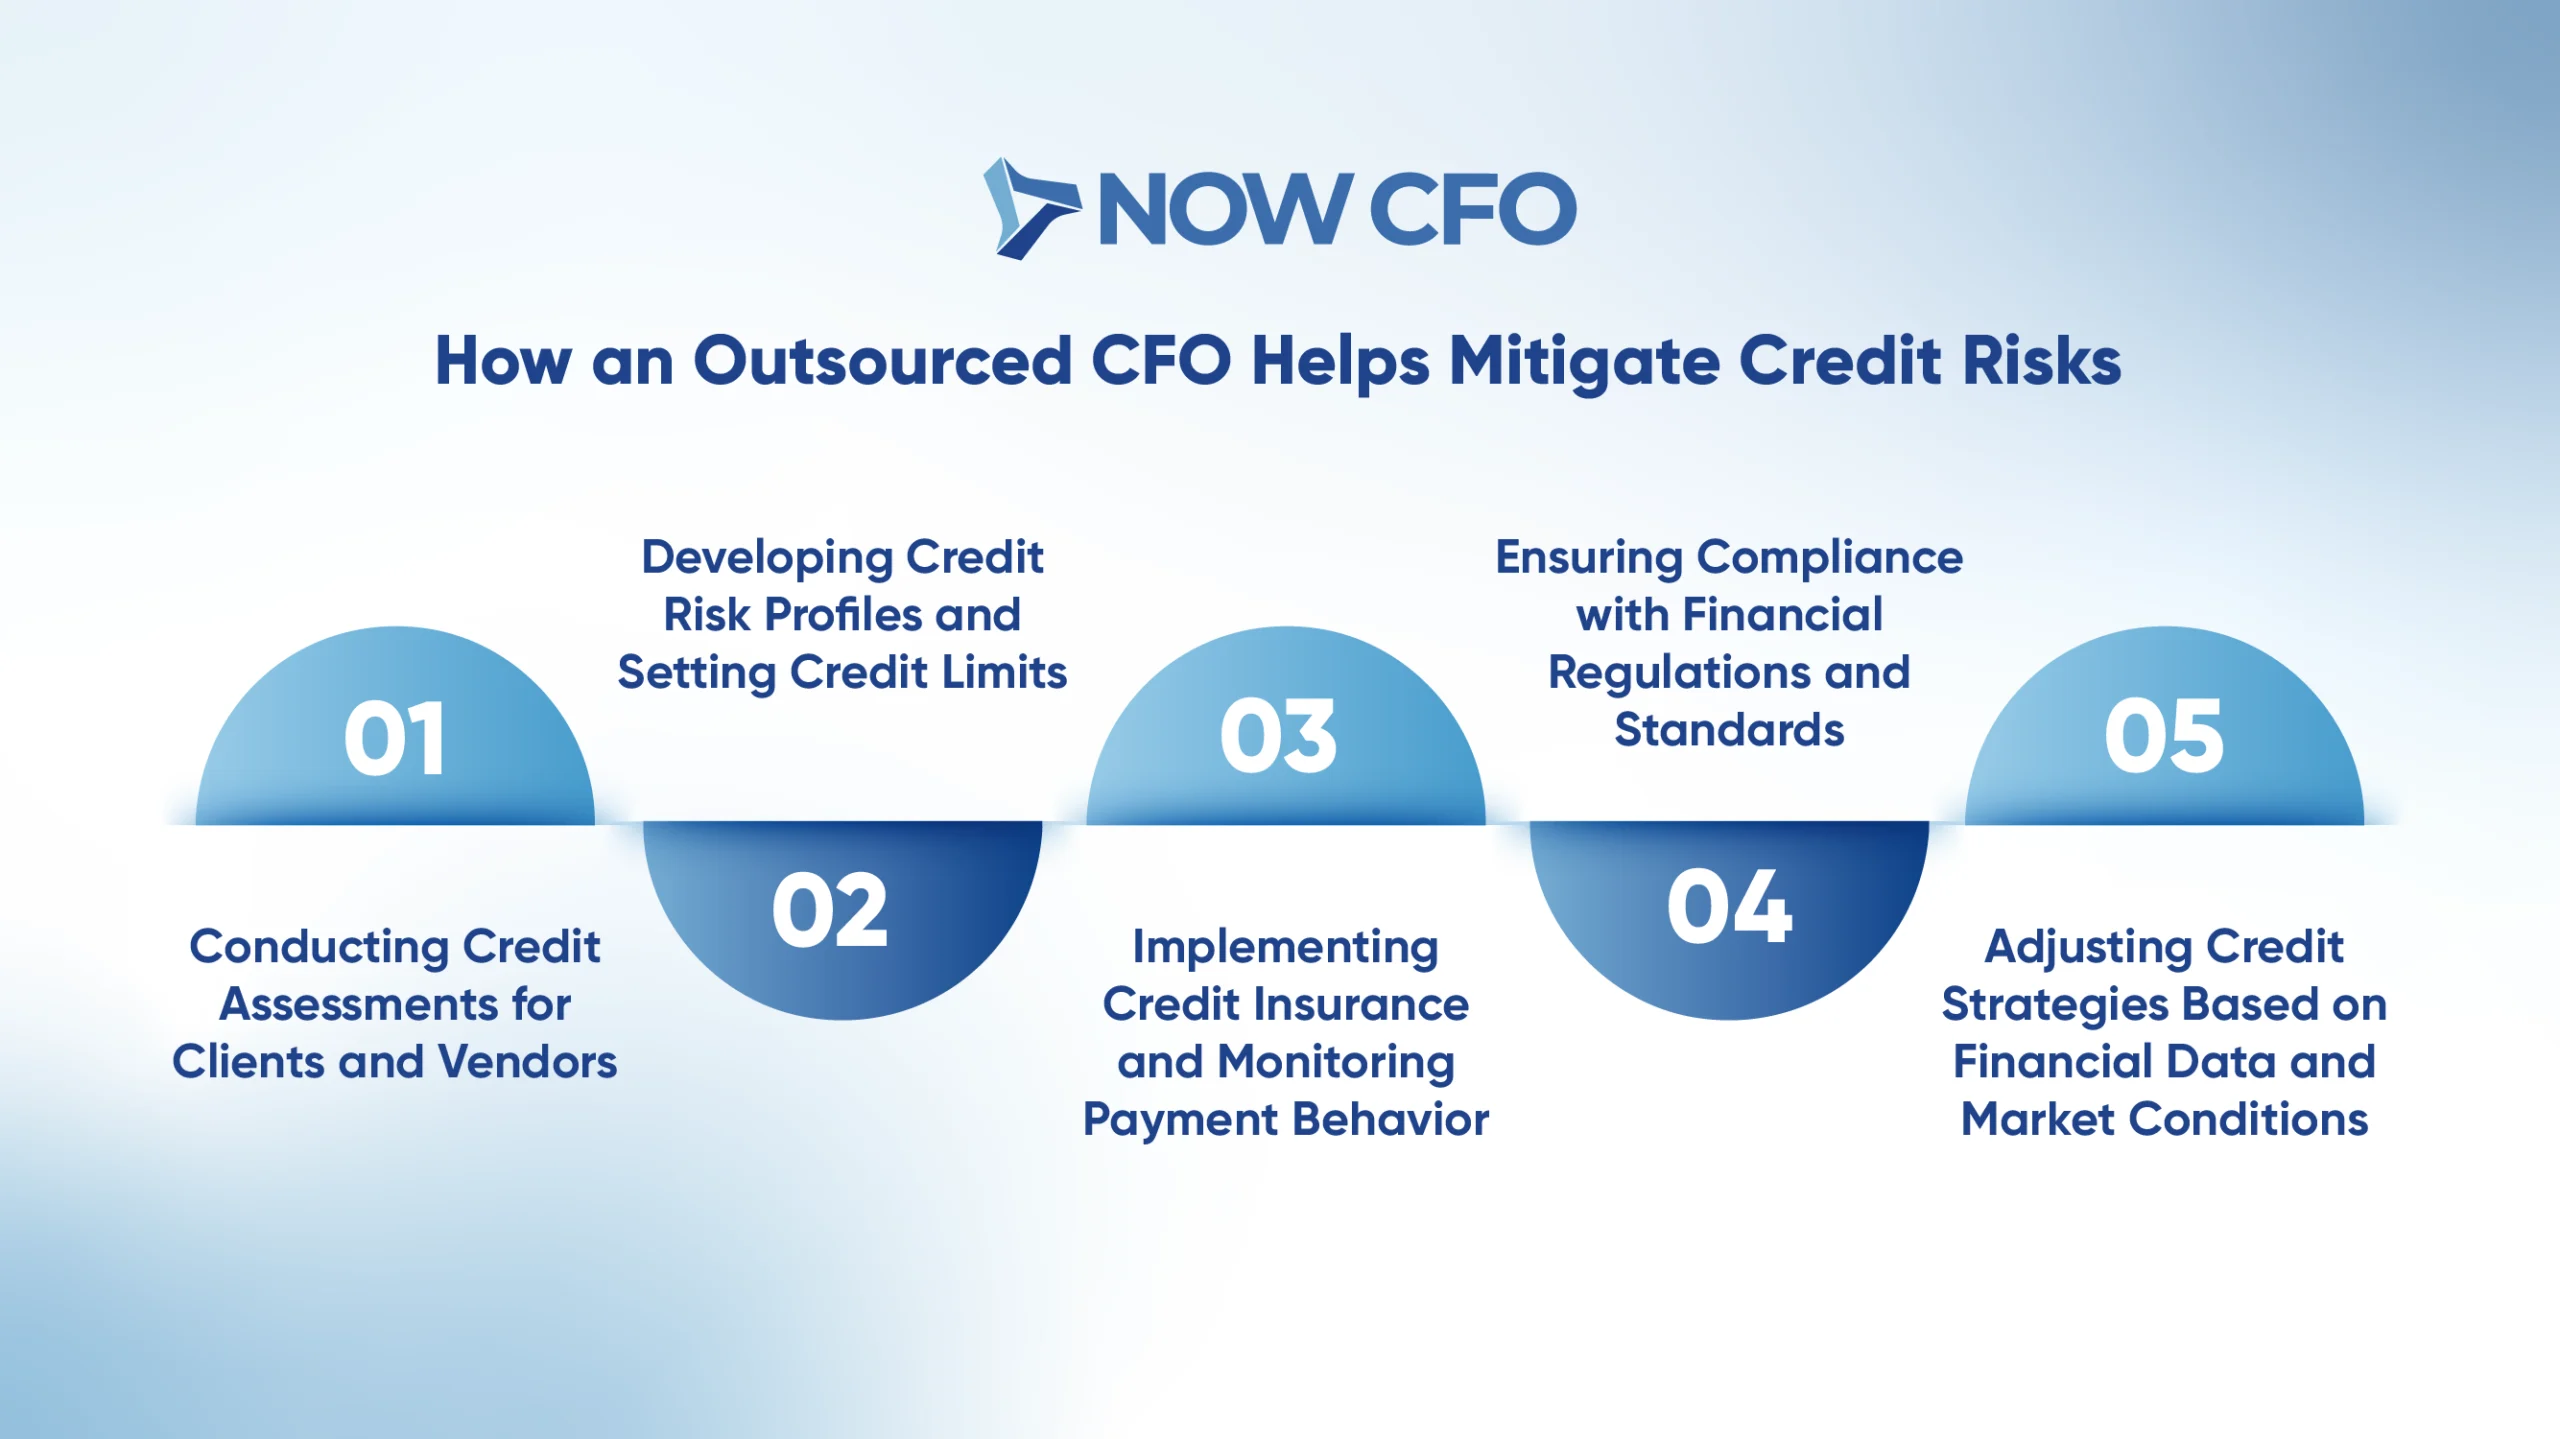
Conducting Credit Assessments for Clients and Vendors
An outsourced CFO establishes formal credit assessment procedures to evaluate both clients and vendors. They analyze financial statements, review credit scores, and evaluate debt-to-equity ratios.
- Standardized Credit Checks: Use D&B or FICO-based models to assess applicant creditworthiness.
- Verify Financial Health: Review of recent audits, cash flow, and profitability trends.
- Check Payment History: Investigate data on late payments or defaults.
Developing Credit Risk Profiles and Setting Credit Limits
With thorough assessments in hand, an outsourced CFO constructs risk profiles categorizing customers by default probability, credit exposure, and payment behavior. They then align credit limits accordingly higher limits for low-risk clients and tighter terms for risky ones.
By calibrating profiles with industry benchmarks and client analysis, they fortify overall credit risk management and minimize unexpected write-offs.
| Risk tier | Typical profile | CFO action |
|---|---|---|
| Low risk | Strong credit score, consistent on-time payment history | Higher limits, standard Net 30-60 terms, early-payment discounts |
| Medium risk | Mixed payment history or limited credit data | Moderate limits, shorter terms, periodic review |
| High risk | Weak score, late-payment or default history, thin financials | Tight limits, prepayment or deposits, credit insurance, close monitoring |
Implementing Credit Insurance and Monitoring Payment Behavior
An outsourced CFO recommends credit insurance to protect significant receivables, especially in international transactions. They also monitor payment trends, flagging customers with increasing DSO or late trends, and trigger corrective actions like payment plan adjustments or limit reductions.
Ensuring Compliance with Financial Regulations and Standards
An outsourced CFO aligns credit policies with pertinent regulations; GAAP, Basel III, SEC, OCC standards; and mandates adherence throughout operations. They ensure allowances for doubtful accounts match GAAP’s aging-based methodology.
Routine policy reviews and compliance audits prevent regulatory breaches and reinforce disciplined credit management strategies.
Adjusting Credit Strategies Based on Financial Data and Market Conditions
Building on monitoring frameworks, an outsourced CFO continuously refines credit tactics based on evolving financial and market conditions.
- Reassess limits quarterly: Adjust based on updated financials or sales volatility.
- Stress-test scenarios: Simulate economic downturns or interest rate hikes to gauge credit risk.
- Alter payment terms: Tighten or relax terms based on changing market dynamics or customer segments.
What Are the Benefits of an Outsourced CFO for Credit Management?
The main benefits are stronger cash flow, lower bad-debt and late-payment risk, clearer client credit terms, and better data for decisions. Each comes from tighter credit policy and faster collections rather than from adding sales.
Enhanced Cash Flow and Liquidity
An outsourced CFO tightens credit policies, accelerates receivables, and reduces working capital gaps. Companies that shorten their cash conversion cycle rely less on short-term credit lines and free up working capital for operations. These improvements directly support CFO cash flow management and credit management strategies, ensuring ample funds for growth.
Reduced Risk of Bad Debts and Late Payments
Tighter policy enforcement drives down payment delays and bad debts:
- Automated overdue alerts and consistent follow-up reduce late payments and shorten the collection cycle.
- Regular reviews flag high-risk accounts early.
- Escalation protocols enforce consistent action.
Improved Client Relationships Through Transparent Credit Policies
Clear, transparent credit terms build stronger client trust and smoother interactions:
- Written payment schedules prevent surprises.
- Open communication builds understanding and loyalty.
- Flexibility, such as early-payment discounts, rewards reliability.
These strategies balance firm boundaries and customer goodwill, enhancing business relationships and supporting credit management services.
Stronger Financial Stability and Risk Management
Outsourced CFOs embed robust credit oversight into broader risk frameworks. They analyze liquidity buffers, stress-test credit outcomes, and align practices with industry benchmarks.
Sound liquidity planning critically improves institutional resilience during downturns. These efforts advance CFO financial health optimization and reinforce credit management strategies at all levels.
Better Decision-Making with Accurate Financial Data
Accurate credit metrics empower data-driven strategy. Outsourced CFOs integrate KPIs into reporting dashboards. Timely, precise data enables strategic credit-limit adjustments, investment decisions, or liquidity planning.
A Simple Cost-of-Waiting Example
Consider a company with $2 million in annual credit sales and a DSO of 60 days. Roughly $329,000 sits in receivables at any moment. Cutting DSO to 40 days through tighter terms and faster collections frees about $110,000 in cash without adding a single sale. That freed cash is working capital the business no longer has to borrow, which is the core of what improved credit management delivers.
Steps to Improve Credit Management with an Outsourced CFO
The steps are: audit current credit policy, set clear terms and limits, monitor client creditworthiness on a schedule, automate credit control, and adjust limits as performance changes. An outsourced CFO runs this cycle so the improvements hold over time.
Conducting a Comprehensive Review of Credit Policies
An outsourced CFO initiates a deep audit of existing credit policies. They examine payment terms, approval workflows, and enforcement measures. This review identifies inconsistencies and uncovers gaps in collection tactics.
They also assess alignment with industry standards and internal objectives. This structured evaluation lays the groundwork to improve credit, ensuring policies drive efficient receivables, consistent risk oversight, and sustainable liquidity.
Setting Clear Credit Terms and Conditions
To bridge policy clarity and operations, the outsourced CFO establishes precise, standardized credit agreements:
- Define payment windows (e.g., Net 30, Net 45) and penalties for late payments.
- Clarify credit limits based on client profile and payment history.
- Include early-payment discounts to encourage timely settlement.
This clarity streamlines collections, builds trust, and improves credit risk management by setting transparent expectations and reducing disputes.
Monitoring Client Creditworthiness Regularly
The outsourced CFO sets up routine reviews to reassess client risk. They track updated financials, payment behaviors, and external credit scores. They also monitor macroeconomic indicators affecting sectors of exposure.
By revisiting credit limits quarterly, businesses can preemptively adjust terms or tighten controls. Systematic monitoring reduces delinquency among SMBs. This vigilance helps improve credit management and strengthens liquidity management.
Implementing Technology to Automate Credit Control
Automation accelerates collections and enriches CFO cash flow management. The outsourced CFO introduces tools like integrated billing platforms, automated reminder systems, and aging-bucket analytics. These systems generate overdue notifications and escalate accounts based on predefined thresholds.
Adjusting Credit Limits Based on Business Performance
An outsourced CFO ensures credit limits remain dynamic and aligned with performance. They correlate client payment trends, sales volumes, and internal cash flow metrics to adjust limits, tightening for riskier clients, increasing for reliable partners.
This ongoing calibration prevents default exposure while supporting loyal customers’ growth. By adapting limits based on real-time data, businesses improve credit management and sustain optimized liquidity ratios.
Learn More: Benefits of hiring an outsourced CFO
How Do You Choose an Outsourced CFO for Credit Management?
Choose an outsourced CFO for credit management by checking five things: proven credit-risk and cash-flow experience, the ability to build credit policy tailored to your business, a track record of measurable results, strong analytical and negotiation skills, and alignment with your financial goals.
Look For Experience in Credit Risk and Cash Flow Management
A top-tier outsourced CFO must demonstrate proven strength in credit risk management and CFO cash flow management. Seek candidates who have handled credit assessment, risk modeling, and liquidity optimization.
- Industry Experience: Ideal candidates should manage these aspects in similar-sized firms or your sector.
- Tangible Results: Ask for metrics, e.g., percentage reduction in DSO or improved liquidity ratios.
- Risk Frameworks: Familiarity with tools such as credit scoring or insurance to mitigate credit risk.
Assess Their Expertise in Developing Customized Credit Policies
An effective outsourced CFO adapts credit policy to your unique business needs, your sales cycle, customer segments, and risk appetite. They design tailored credit terms, limits, and enforcement structures.
They integrate industry best practices and compliance mandates, and align policies with strategic goals. This depth ensures your credit management strategies are not generic but precisely optimized for your operations and risk profile.
Verify Their Track Record in Improving Financial Health
Look for CFOs who have demonstrably transformed companies’ credit performance. Request past case studies showing improved cash flow, reduced bad debt, or optimized credit limits.
- Verified Improvement: E.g., “increased cash-on-hand by 20% through tightened credit policy.”
- Documented Outcomes: Financial reports or references confirming results.
Ensure Strong Analytical and Negotiation Skills
A savvy outsourced CFO combines analytical rigor, interpreting credit metrics and market data, with negotiation finesse
- Analytical Capability: Ability to evaluate DSO trends, aging reports, and forecast impacts.
- Negotiation Skill: Can renegotiate terms or credit limits with clients.
Confirm Their Alignment with Your Financial Goals
Your outsourced CFO should fully understand and align with your long-term financial ambitions, whether rapid growth, stable liquidity, or gearing for investment. They assess your business model, stage, and cash flow patterns, and tailor credit strategies accordingly.
Getting Started With an Outsourced CFO for Credit Management
Getting started is straightforward: an outsourced CFO reviews your current credit policy, finds where cash is getting stuck, and puts risk-based terms and collection routines in place. That structure reduces financing roadblocks and strengthens your standing with lenders as you grow.
Ready to strengthen your credit control and liquidity strategy? Schedule a free consultation with NOW CFO’s finance team today and take the next confident step toward financial strength.
Frequently Asked
Disclaimer: This content is for general information only and isn’t a substitute for professional accounting, tax, or financial advice. For guidance specific to your business, contact NOW CFO.


